The distinction between an employee and a contractor can mean a significant difference in costs for a company. However, if the contractor relationship is structured incorrectly, the savings may be offset by audits, back taxes and social security contributions, or penalties. So where exactly is the line between a legitimate business relationship and the “Švarc system”? And can, for example, a salesperson in a shopping center legitimately operate as a sole proprietor or a limited liability company (s.r.o.)?
The “Švarc system” is one of Slovakia’s perennial business practices. The reason is relatively simple: there is a significant difference between employment and a contractor relationship in terms of the tax and social security burden, as well as the legal status of both parties.
At the same time, however, it is not just a matter of mathematics. The key question is when a person should be considered an employee and when they can still carry out their activities as a self-employed individual or through their own limited liability company.
At Highgate Group, we have been addressing this very issue for a long time, not only from the perspective of labor law, but also in terms of taxes, social security contributions, and the practical arrangements governing relationships between companies and contractors.
The motivation of both business owners and employees is largely economic.
If a company has a specific budget per person, the resulting net amount can vary significantly between an employment relationship and a contractor relationship. In the lecture, we illustrated this difference using the example of a person with a total budget of 3,000 euros. In an employment relationship, a significant portion of the costs goes toward taxes and social security contributions, whereas when operating as a limited liability company (s.r.o.), the overall tax burden can be substantially lower.
However, the difference is not limited to taxes and social security contributions.
Labor law protects employees and significantly limits the parties’ freedom to contract. This can be a problem for business owners, for example, when they need an employee to guarantee a specific result or to bear the financial consequences of failing to fulfill an obligation.
Let’s imagine a small store in a shopping center. The lease agreement requires the store to open every day at 9:00 a.m. If an employee fails to show up, the business owner may face contractual penalties or other consequences from the landlord. However, given the protective nature of labor law, the options for passing these consequences on to the employee are limited.
A contractor relationship works fundamentally differently—the contractor bears their own business risk, and liability can be structured much more flexibly.
All of this creates a strong economic and legal incentive to use contractors.
The basis is the concept of dependent work.
According to the current Labor Code, dependent work is work performed within a relationship of superiority between the employer and subordination of the employee, personally by the employee for the employer, according to the employer’s instructions and on the employer’s behalf. At the same time, dependent work cannot be performed under a civil or commercial contractual relationship.
The Act on Illegal Work and Illegal Employment subsequently addresses the use of dependent labor without establishing the appropriate employment relationship.
At first glance, the rule may seem simple. In practice, however, problems arise when interpreting the individual characteristics of dependent work.
What exactly do “superiority” and “subordination” mean? When is work being performed according to instructions, and when is it simply a legitimate assignment of a task to a business partner? And what exactly does it mean to perform work on behalf of an employer?
Business relationships are naturally full of instructions, deadlines, requirements, and performance reviews. The mere existence of instructions, therefore, does not automatically provide a simple answer to the question of whether the work is performed under a relationship of subordination.
The difference may also lie in the practical arrangement of the relationship. There’s a difference between telling a contractor, “These are your shifts; this is when you’ll be working,” and asking them, “When can you provide this service?”
It is therefore the actual functioning of the collaboration that is of paramount importance when assessing the “Švarc” system.
One of the most common misconceptions is the idea that the risks associated with the “Švarc” system can be resolved by a properly titled contract or by invoicing through a sole proprietorship or a limited liability company.
It won’t solve the problem.
The Labor Inspectorate may examine not only legal documents but also how the relationship actually functions. Therefore, simply labeling a contract as a commercial partnership is not decisive.
Similarly, one cannot automatically assume that establishing a limited liability company (s.r.o.) will eliminate the problem of the “Švarc system.”
However, from the perspective of legal argumentation, the status of a limited liability company (S.r.o.) may be a relevant factor. One of the purposes of labor law is, in fact, to protect the weaker individual, including through rules governing liability for damages. In a business relationship between two companies, the status of the parties may differ significantly.
However, that still doesn’t mean that every transaction conducted through a limited liability company is automatically safe.
When making this assessment, it is necessary to analyze the entire set of facts: the contractor’s degree of independence, the manner in which the work is assigned, the contractor’s responsibilities, economic status, and the way the work is organized, as well as the actual purpose of the chosen model.
Business owners sometimes view the “Švarc” system primarily as a labor law risk. In reality, the problem can have much broader consequences.
If the regulatory authority concludes that the declared business relationship was, in fact, dependent employment, the issue may also extend to tax and social security contributions.
The consequences may not be limited to penalties for illegal employment. This could potentially lead to claims for advance tax payments, social security and health insurance contributions, interest, and other related claims.
Therefore, when there are a larger number of contractors, the economic impact on the company can be very significant.
In addition, another issue arises in practice: the tax deductibility of expenses related to contractors, such as vehicles or computer equipment used by contractors. The “Švarc system” cannot, therefore, be viewed solely in terms of labor law.
There is no one-size-fits-all answer. Every relationship must be evaluated based on its specific circumstances and how it actually works.
However, in our view, a legal assessment should not consist merely of mechanically checking off the individual characteristics of dependent employment. The meaning and purpose of labor law regulations are also important—particularly the protection of the weaker party where there is a real economic and organizational imbalance between the parties.
The situation may be different for a person who is effectively dependent on a single “employer” and has no real bargaining power, compared to that of an economically independent contractor who consciously runs a business, bears their own risks, and has a real opportunity to choose the form of cooperation.
At the same time, the more a contractor’s actual work resembles that of a traditional employee—particularly in terms of supervision, personal performance, instructions, and acting on behalf of the other party—the higher the risk of the relationship being reclassified.
The situation can be equally problematic if it is evident from the circumstances that the primary purpose of the contractor model was merely to replace an employment relationship in order to reduce taxes and social security contributions.
That is why, when establishing a partnership, it is not enough to simply draw up a good contract. The contract, the economic nature of the relationship, and its day-to-day operations must all be on the same page.
At Highgate Group, we take a comprehensive approach to the “Švarc system”—from the perspectives of labor law, taxation, and social security contributions. We help companies analyze their existing contractor models, identify risk factors, and structure their partnerships to reflect the true nature of the business relationship.
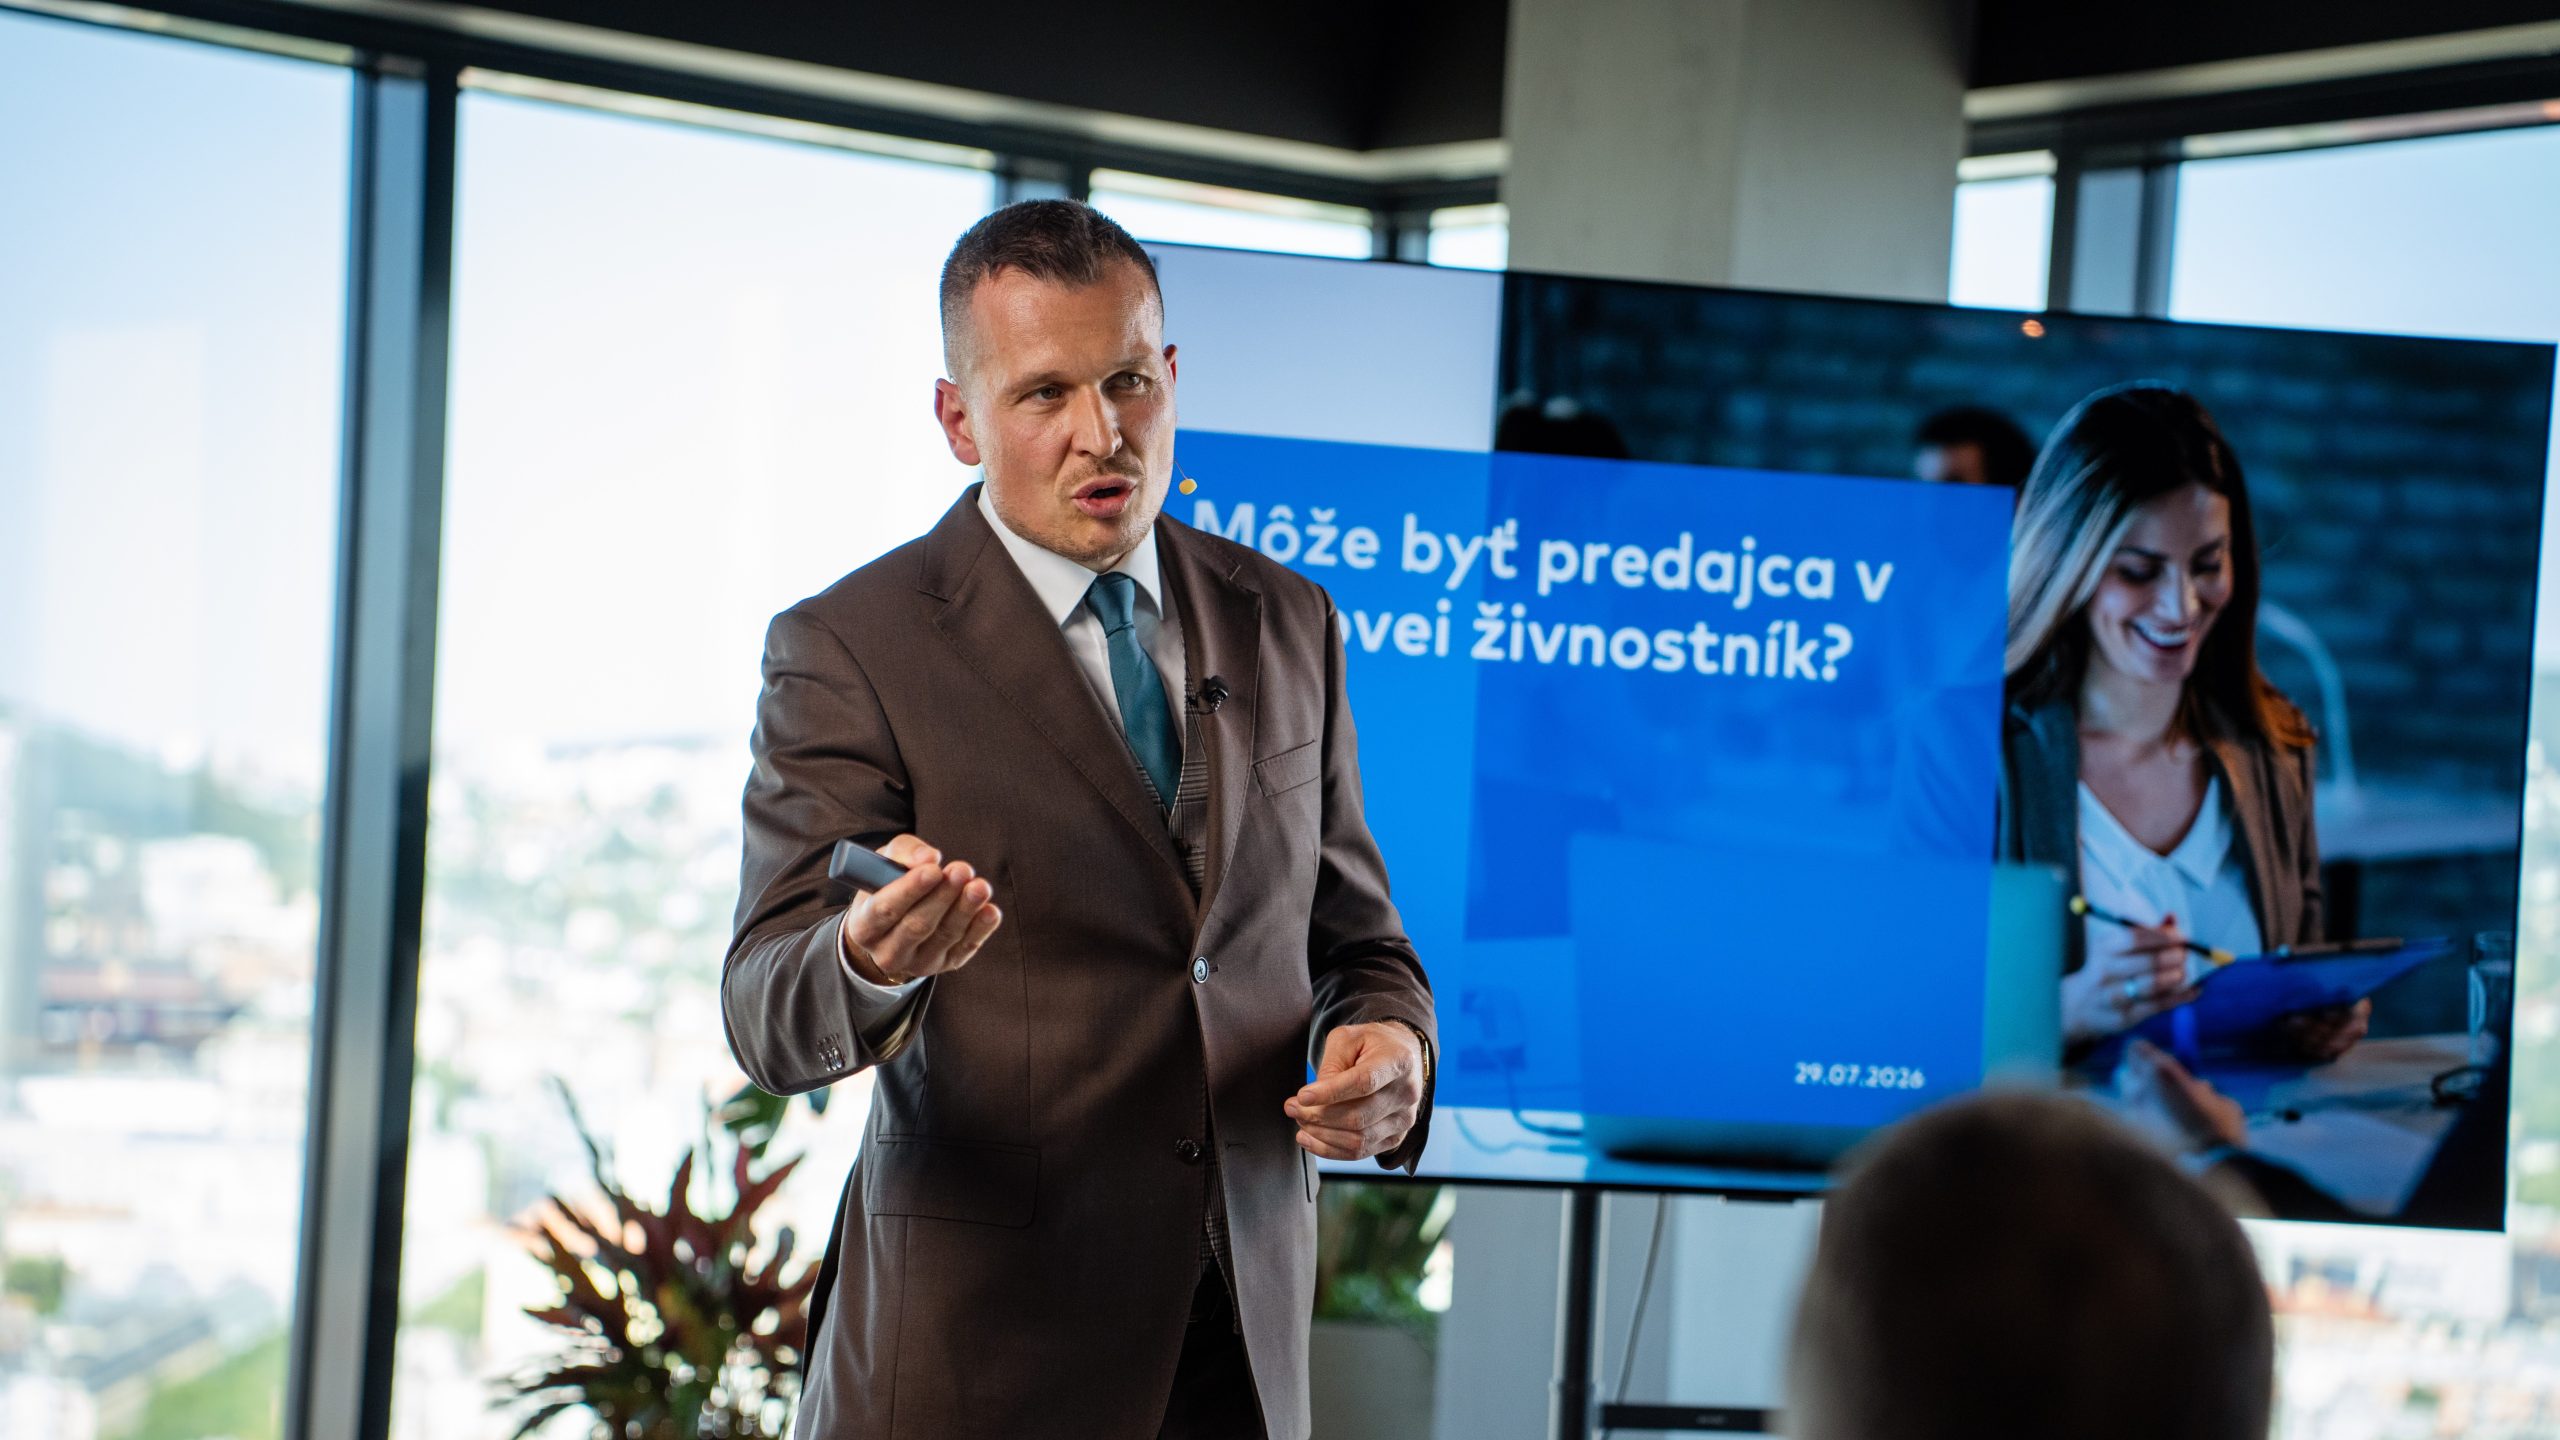
We also discuss this entire topic, including a detailed legal analysis, in the lecture featured in the video at the end of the article.
We will also address the topic of setting up a business in an efficient and legally sound manner at our conference “Why and How to Stay in Slovakia?”, where we’ll examine practical legal and tax options for doing business in Slovakia and abroad.
We are the Highgate Group, modern advisors for your law, tax and accounting under one roof.
You can find more information about the Švarc system on our website in this section: “Employment” of Self-Employed Individuals (Švarc System)
If you’re interested, you can subscribe to our newsletter featuring interesting and practical legal and tax information.
You can address your specific questions during a consultation with our partner, Peter Varga, who specializes in financial regulation and tax law. You can schedule a consultation here.